The ROI of Commercial Roof Replacement: How to Calculate Payback Period
Published March 2026 · Ocean Group Construction
Building owners often treat roof replacement as a capital expense to defer. A better decision model compares verified scope, current operating consequences, financing, hold period and documented alternatives without assuming a universal return.
Here's how to build the ROI case for your specific building.
The ROI Framework
The formula is straightforward:
ROI = (Annual Benefits ÷ Total Replacement Cost) × 100
Payback Period = Total Cost ÷ Annual Benefits
The components of "Annual Benefits" are where most building owners leave money on the table because they only count energy savings. The full picture includes five categories.
Category 1: Energy Savings
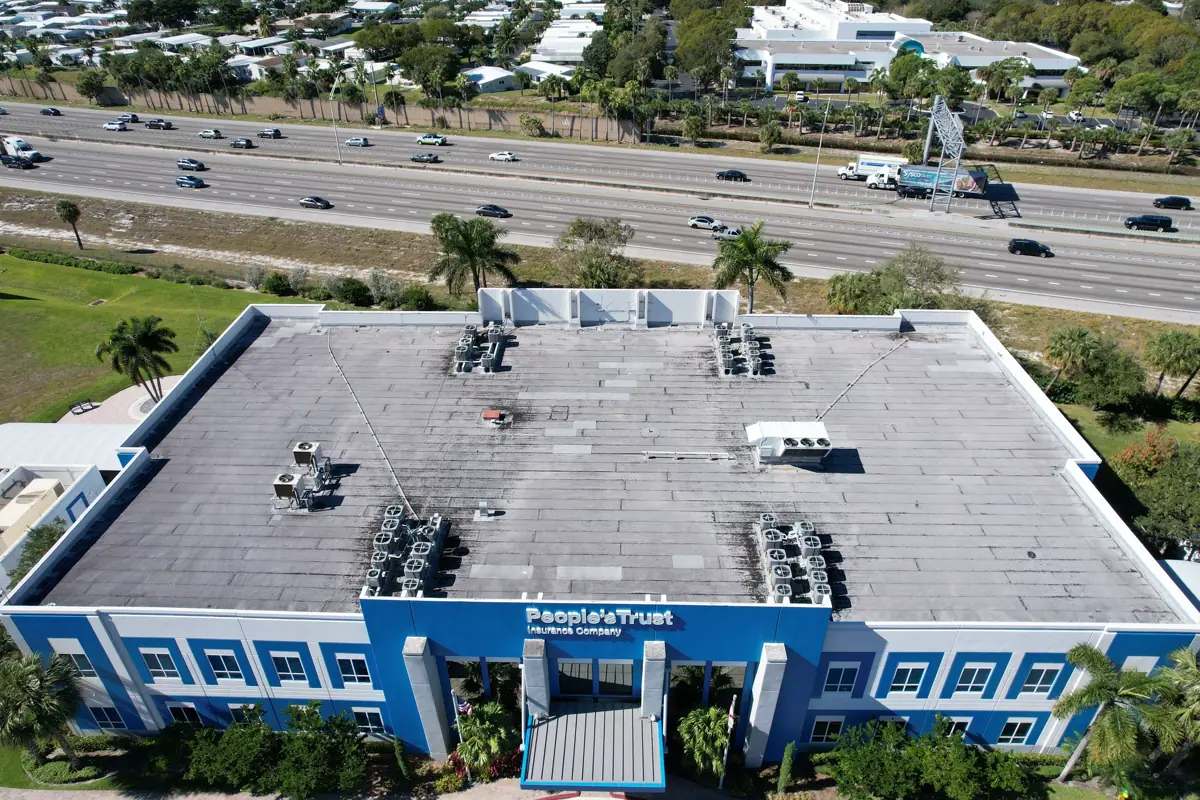
A reflective white TPO or PVC membrane with an SRI (Solar Reflectance Index) above 90 reduces rooftop surface temperatures by 50–80°F compared to an aged dark membrane. That directly reduces the HVAC cooling load for the building below.
Reflectance can be one input in a Florida energy analysis, but whole-building results depend on insulation, HVAC, occupancy, geometry, existing conditions and operations. Use a qualified building-specific model before assigning savings.
Category 2: Avoided Repair Costs
Want to know what this means for your roof?
One call. We'll tell you exactly where you stand.
Call 786-696-4829An aging roof in its last 5 years of life doesn't just sit there quietly. It generates maintenance costs — emergency patches, drain repairs, flashing remediation, interior damage cleanup from leaks. These costs compound as the system deteriorates.
Use the property's actual repair invoices, leak history, moisture findings and disruption records to compare continued repair with replacement. A new roof does not eliminate all service or maintenance obligations.
For the full escalation math, see our analysis of the true cost of deferred roof maintenance — it shows the 10-year cost curve on a maintained vs. neglected Florida commercial roof.
Category 3: Insurance Premium Reduction
This one surprises building owners who haven't shopped their property insurance since they got the building. In Florida's post-Ian, post-Irma insurance market, roof age and condition are among the most significant rating factors for commercial property policies.
A building with a 20-year-old roof in unknown condition faces higher premiums, higher deductibles (wind/hail deductibles on old roofs can be 3–5% of building value), and increasingly, non-renewal or coverage limitations from carriers.
A new compliant roof — properly documented, with manufacturer warranty in place — can result in:
- Potential changes to wind/hail deductibles, subject to the carrier and policy
- Potential premium or underwriting changes that only the insurer can confirm
- Coverage available from carriers who had previously declined to quote
Do not assign an insurance savings amount without written confirmation from the carrier or broker. A permitted roof and closeout file may support underwriting review, but no reduction is guaranteed.
Category 4: Property Value Increase
Commercial real estate appraisers use the income approach, the sales comparison approach, and the cost approach. In the cost approach, remaining useful life of major building systems — including roofing — directly affects appraised value. A building with a roof that needs replacement in the next 2 years carries a deduction against its appraised value equal to the estimated replacement cost.
A documented roof condition can affect transaction diligence, but market value depends on the property, buyer, income, cap rate and appraisal. Obtain valuation advice before assigning a return.
Category 5: Warranty Value
An issued, transferable manufacturer warranty can be relevant to diligence, but it does not represent zero maintenance risk. Review the exact coverage, exclusions, owner duties and transfer process.
The Full ROI Example: 15,000 Sq Ft Florida Commercial Building
Property-Specific Replacement Decision Model
Calculate payback only from documented inputs and scenario-test the owner's actual hold period. Do not count unconfirmed energy, insurance, tax or appraisal effects as guaranteed benefits.
If you're planning to sell in the next 5 years, the calculation looks even better — the property value uplift and deductible reduction hit immediately, and you capture them at sale.
Section 179D: The Tax Deduction Most Owners Don't Claim
The Energy Efficient Commercial Buildings Deduction (Section 179D of the IRS tax code) allows commercial building owners to deduct the cost of energy-efficient building improvements, including qualifying roof replacements, in the year the improvement is placed in service.
This is a real deduction available to commercial property owners who replace aging roofs with energy-efficient systems. Most don't claim it because their contractor didn't mention it. We mention it.
Financing Options: You Don't Have to Pay It All Upfront
PACE Financing
PACE terms, availability, property eligibility, lien treatment and closing implications vary. Review current program documents with financial and legal advisers before relying on it.
Manufacturer Programs
Carlisle, GAF, and Firestone all offer financing programs through approved contractors. Typically 24–60 month terms, sometimes with deferred payment options. Useful for bridging between capital budget cycles.
Traditional Commercial Lending
Capital improvement loans or lines of credit from commercial banks. Rates vary with the rate environment, but the ROI analysis above makes a compelling case for positive leverage when the annual benefit exceeds financing cost.
How This Connects to Ongoing Maintenance
The ROI math above assumes the new roof is maintained — annual inspections, drain cleaning, documented upkeep. A new roof that isn't maintained will deteriorate faster and won't deliver the full projected life. The warranty requires it, and the investment case depends on it.
See our silicone coating vs. replacement analysis for a parallel look at when restoration is the better financial choice. Our reroofing vs. coating restoration decision guide walks through the core cut inspection process that determines which path is right. And our roof lifespan by system guide shows what to expect from each system over its service life in Florida's specific climate. If you're not yet sure your roof needs replacement, see our guide to commercial roof replacement signs for the indicators that make the decision clear.
If you manage multiple commercial properties, this framework applies at portfolio level too. See our property manager services page for how we structure multi-building maintenance and replacement programs.
The Bottom Line
Roof replacement is a capital decision that should be modeled with verified scope, actual operating records and clearly separated assumptions. OGC can document roofing scope and closeout; owners should use qualified professionals for energy, insurance, tax and valuation conclusions.
Run the analysis before you decide to defer. You may find the cost of waiting — in escalating repairs, increasing insurance costs, and deteriorating property value — exceeds the cost of acting now.
We'll walk you through the numbers for your specific building. No obligation.